
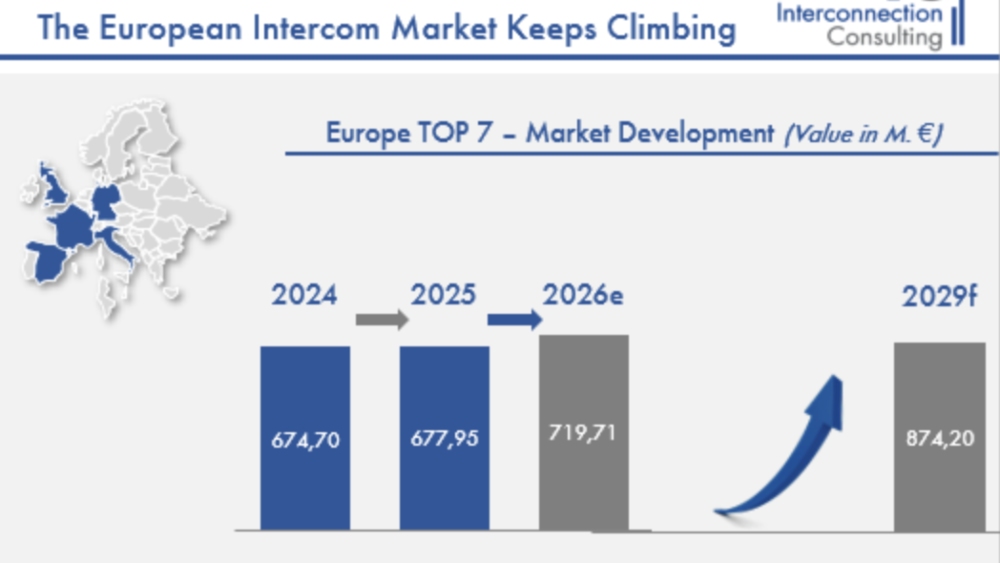
The European door intercom market is forecast to grow from €677.9 million in 2025 to €873.8 million by 2029, according to a new study by Interconnection Consulting covering Italy, Germany, Austria, France, Spain, Switzerland and the United Kingdom.
Behind this overall growth trajectory, however, three forces are reshaping demand at very different speeds: video is overtaking audio-only technology, but unevenly across the region; new construction and renovation activity are moving at different paces from one country to the next; and IP-based technology is redrawing the competitive map far faster in some markets than in others.
IP-based systems are forecast to grow from 21.9% of installed units in 2025 to 31.0% by 2029 across the seven markets – but that average hides a sharp divide.
The United Kingdom already leads with 31.1% IP penetration in 2025, more than double Italy’s 11.7%.
The study finds this gap holds steady all the way through 2029, rather than narrowing as the technology matures.
Three factors help explain the difference.
Specialised installers make up a far larger share of the trade in the UK than in Italy, and adapting to a more complex, less familiar technology depends heavily on having a base of installers who are skilled and genuinely comfortable working with it.
Building type also plays a role: 51.4% of the UK market consists of detached houses, where a single owner can decide alone, compared with 30.1% in Italy, where multi-unit buildings dominate and replacing a shared system such as an entry panel requires the approval of the building’s assembly.
Furthermore, manufacturers focused specifically on IP systems already account for 31.6% of market volume in the UK, against just 1.5% in Italy. No single factor fully explains the divide; together, they show why the shift is playing out at different speeds market by market.
This distinction between established local manufacturers and newer IP-focused entrants also helps explain the broader competitive landscape across Europe, not only the differences between the UK and Italy.
Across all seven markets, the top ten manufacturers by volume hold 63.6% of the total market: concentrated at the top, certainly, but leaving more than a third of the field still up for grabs.
The European market remains fragmented, leaving substantial market volume outside the top ten manufacturers.
Competitive structures also differ significantly by country, with established local players remaining dominant in some markets while IP-focused entrants are gaining ground in others.
The latest market data reveal a more differentiated picture.
Three of the seven markets contracted or remained broadly stagnant between 2024 and 2025, including two of Europe’s largest markets.
Spain, by contrast, recorded value growth of 8.3% over the same period – the strongest performance among the seven countries analysed.
The study indicates that Spain’s performance is not simply a one-off.
Over the past several years, its construction activity has remained more stable than in the other six markets analysed, which experienced more pronounced fluctuations during the pandemic and again in 2024.
Over the same period, Spain has also been one of the fastest markets shifting toward audio-plus-video systems, already close to half its installed base by 2025.
A stable foundation and an upgrading product mix, in other words, are now showing up together in the numbers.
The forecast presents a different picture. France – the market that declined between 2024 and 2025 – is expected to record the highest value growth among the seven countries through 2029, with a CAGR of 9.3%.
The market that just went through a rough patch turns out to be the one re-stabilising fastest and pulling ahead over the long run. The lesson: a strong single year is not the same as a strong trajectory.
Spain delivered the strongest performance in 2024–2025, but the current forecast suggests that the next phase of growth will favour markets recovering from a deeper correction rather than those that remained comparatively stable.
The shift from audio-only to audio-plus-video systems is real, but it is far less uniform and far less sudden, than commonly assumed.
At the aggregate European level, audio-plus-video is not forecast to overtake audio-only in unit volume until 2029 and even then only four of the seven markets studied will have completed the shift to a video-majority installed base; the other three are expected to remain audio-majority through the end of the decade.
Audio-only, in other words, is on its way out – but this is not a market that collapses overnight. It is a long, gradual fade and for at least the next several years, audio-only systems will still represent a very real, sizeable part of the business, just unevenly distributed across the continent.
That, in the end, is the central message: this is no longer one European market moving at one speed — and the companies still treating it that way are the ones already falling behind.
